
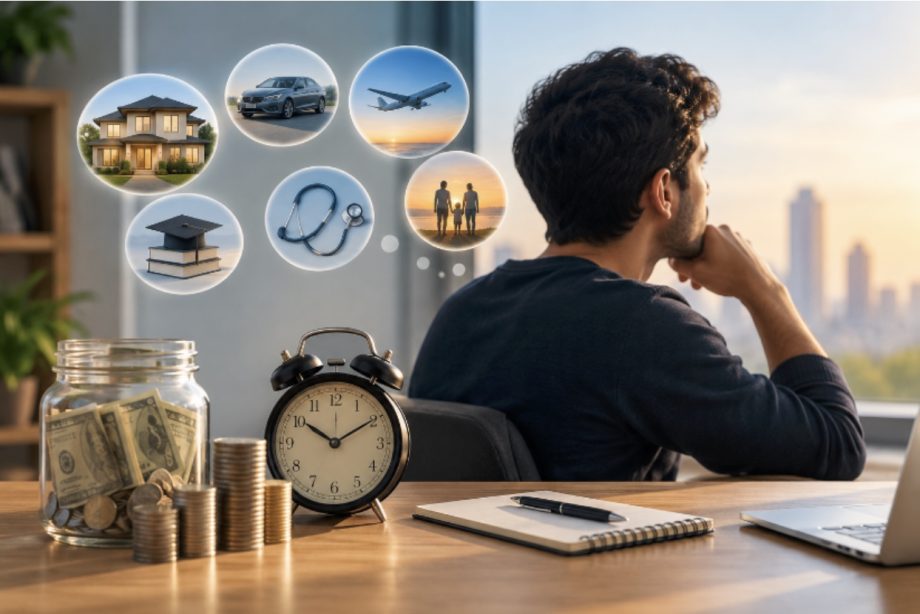
Most people hear the word liquidity and think of investing. They picture stocks, bonds, and whether an asset can be turned into cash quickly. That is true, but in everyday life liquidity matters even more as a form of breathing room. It is the gap between a problem showing up and you being forced to make a bad decision because the clock is ticking.
That is why cash on hand is not just a financial metric. It is a kind of control. When your checking or savings balance gives you a little runway, you can compare options, wait for better timing, and avoid reacting out of panic. The same logic applies when you are dealing with debt. Instead of rushing into the first offer you see, you have time to look into reputable debt relief companies and weigh what actually helps your situation.
The Real Benefit Is Not the Cash Itself
Liquidity is often described as access to cash or assets that can be converted to cash easily. Investor.gov explains liquidity in terms of how easily something can be sold without taking a significant hit, and FINRA emphasizes keeping emergency money somewhere accessible without penalties or major risk. Those are useful definitions, but the practical takeaway is simpler: liquidity buys you time to think. Investor.gov’s explanation of liquidity makes that point clear in financial terms.
That time matters because emergencies rarely arrive one at a time. A car repair can show up during a slow work month. A medical bill can land right as rent is due. A job loss can happen in the middle of a market dip. If all your resources are locked up, you may be forced to sell something at the wrong moment, borrow at a painful interest rate, or skip a better long term choice because you need a fast fix today.
When You Lack Liquidity, Everything Gets More Expensive
People often focus on the direct cost of a crisis. The repair costs six hundred dollars. The missed paycheck is two thousand. But the hidden cost is what happens when you have no runway. You may pull money from an investment during a downturn. You may use a credit card because it is the only immediate option. You may accept terms you would normally reject simply because you need relief now, not next week.
This is where liquidity changes the whole experience. It does not always erase the problem, but it lowers the price of solving it. A person with a cash cushion can call around for estimates, negotiate a payment plan, or wait a few days before selling an asset. A person without that cushion often has to take the fastest option, not the smartest one.
Liquidity Protects Long Term Plans From Short Term Chaos
There is another angle people miss. Liquidity is not the opposite of investing. In many cases, it protects your investments. FINRA notes that an emergency fund can help you avoid taking on substantial debt or liquidating investments to cover unexpected expenses. That matters because good long term plans often fail for very short term reasons. FINRA’s guidance on emergency funds and financial foundations highlights how accessible savings can keep a temporary setback from derailing a larger strategy.
Imagine building a retirement account for years, then needing cash during a bad market stretch. If you have no liquid reserve, you may have to sell when prices are down. The issue is not that the investment was wrong. The issue is that your timing was chosen by an emergency. Liquidity helps separate urgent needs from long term assets, which gives each part of your financial life a better chance to do its job.
A Small Cushion Still Changes Behavior
A lot of advice makes liquidity sound like an all or nothing target. Either you have six months of expenses saved or you have failed. Real life is messier than that. Even a modest cash reserve can improve decision making. A few hundred dollars might cover a deductible, prevent an overdraft spiral, or let you pay for transportation to keep working. Small reserves create small delays, and small delays can be enough to think clearly.
That shift is important because panic compresses your choices. When every bill feels immediate, the brain starts solving only for today. Liquidity opens the frame back up. It allows you to ask better questions. Is this expense urgent or just loud? Can this be negotiated? Is this the right time to sell? Do I need a loan, or do I need a plan?
Liquidity Is Also About What Not to Lock Up
Building liquidity is not only about saving more. It is also about being careful where you place your money. Some assets may look stable or profitable, but if they are hard to access, they may not help when real life gets complicated. Investor education sources regularly connect asset allocation with time horizon and risk tolerance, and cash remains part of that mix for a reason. If money might be needed soon, flexibility matters as much as return.
That does not mean you should keep everything in cash. It means your financial setup should reflect actual life, not just ideal conditions. Bills come monthly. Income can change. Emergencies do not wait for markets to recover. Liquidity respects that reality.
Time to Think Is a Financial Asset
The strongest reason to value liquidity is psychological as much as mathematical. When you are not cornered, you think better. You compare instead of grabbing. You plan instead of reacting. You preserve options instead of shrinking them.
In that sense, liquidity is not lazy money sitting on the sidelines. It is active protection against rushed decisions. It keeps temporary pressure from causing permanent damage. And when life gets noisy, that extra time can be the difference between a manageable setback and a costly mistake.
If you want a practical way to think about it, stop asking only, “How much am I earning on this money?” Also ask, “How much time would this give me if something went wrong?” That question gets to the real value of liquidity. It gives you the one thing people almost always need most in a financial emergency: enough time to think.
Photo created in AI
Contributed posts are advertisements written by third parties who have paid Woman Around Town for publication.